
Top Glove's 43-Billion-Piece Turnaround: How US Tariffs on China Are Rewiring Malaysia's Glove Trade
When Top Glove Corp Bhd (KL:TOPGLOV) gathered analysts in Kuala Lumpur on March 20, 2025 for its second-quarter results briefing, the numbers on the table told a story far bigger than one company's income statement. The glove maker — a bellwether for the entire medical consumables trade in Malaysia — had just swung back into profit after a bruising downturn, and management insisted it could still ship 43 billion gloves in the financial year ending Aug 31, 2025. Yet almost every line of that story runs through the same fault lines: American tariff policy aimed at Chinese competitors, a European market suddenly flooded with diverted Chinese goods, and a domestic cost base that is rising just as pricing power remains fragile.
This deep dive unpacks the quarter, the target and the machinery behind them — utilisation rates, regional sales mixes, labour-cost inflation and dividend politics — and asks whether the recovery is structural or merely a tariff-induced window that could close as quickly as it opened.
The 43-billion-piece bet: a target that forces a strong second half
Top Glove's sales target for FY2025 is roughly 43 billion pieces of gloves. That figure, reiterated by managing director Lim Cheong Guan at the briefing, is the anchor of the whole investment case. The company disclosed that sales in the first half of the financial year — the six months ended Feb 28, 2025 — came in "slightly below" half of that target. The arithmetic is unforgiving: if the first half delivered a little under 21.5 billion pieces, the second half must deliver a little over 21.5 billion, meaning volumes have to accelerate from here, not merely hold.
Management's confidence rests on three pillars. The first is the United States market, where new import tariffs on Chinese gloves are, in the company's telling, handing Malaysian producers a pricing advantage they have not enjoyed for years. The second is raw materials: falling prices for the inputs that go into natural rubber and nitrile gloves give Top Glove room to price flexibly — to compete for volume where it needs volume, and to defend margin where it can. The third is the developing world, where per-capita glove consumption remains a fraction of Western levels and where, as Lim Cheong Guan put it, the group sees opportunities to sell more.
None of these pillars is unconditional. Tariff advantages depend on Washington's policy choices, which in 2025 have changed direction more than once within single quarters. Raw-material tailwinds benefit competitors as well. And developing-market demand is real but price-sensitive, which collides with the company's rising cost base at home. The 43-billion target is therefore best read as a statement of intent about the second half — a commitment that Top Glove believes demand redirection from China will be large enough, and durable enough, to fill its production lines.
Back in the black: what the second-quarter numbers actually show
The headline quarter — 2QFY2025, the three months ended Feb 28, 2025 — was a genuine turnaround, not a statistical artefact. Top Glove posted a net profit of RM30.28 million, against a net loss of RM51.2 million in the same quarter a year earlier. Revenue rose 60.6% year on year, from RM550.33 million to RM883.65 million. For the full first half, the group reported a net profit of RM35.76 million and revenue of RM1.77 billion, compared with RM1.04 billion in the corresponding period a year before. The Edge Malaysia's coverage of the result itself noted that it was another quarter in the black as sales surged.
Stripping the numbers down to their drivers gives a clearer picture of recovery quality:
- Revenue growth of 60.6% in the quarter — driven by a surge in sales volumes and better pricing versus the depressed levels of early 2024.
- A profit swing of roughly RM81.5 million between 2QFY2024's RM51.2 million loss and 2QFY2025's RM30.28 million profit.
- Utilisation of 58%, up from 40% a year earlier — the single most important operational metric, because glove manufacturing is capital-intensive and fixed costs only dilute as lines run fuller.
- Half-year revenue of RM1.77 billion, up from RM1.04 billion, with a half-year profit of RM35.76 million cementing the exit from the loss-making period.
Two qualifications matter. First, the profit, while real, is thin relative to the revenue base: RM30.28 million of net profit on RM883.65 million of quarterly revenue is a low-single-digit margin, characteristic of an industry still climbing out of oversupply rather than one enjoying pricing power. Second, the internal split of the half is revealing: the RM35.76 million first-half profit against the quarter's RM30.28 million implies that 1QFY2025 contributed only about RM5.5 million, meaning profitability strengthened sharply in sequence through the half. That trajectory is encouraging, but it also shows how recently the company was still operating close to breakeven.
Utilisation: from 40% to 58%, and the long climb to 70%
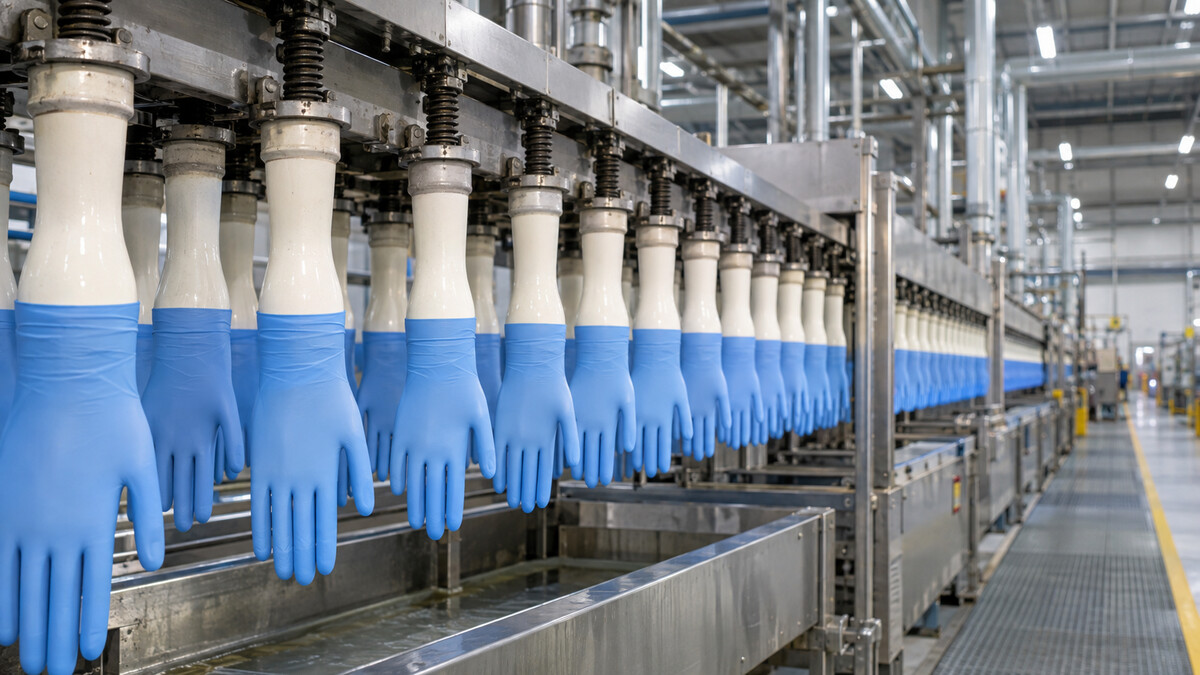
In glove manufacturing, utilisation is destiny. A plant that runs at 40% of capacity carries roughly the same depreciation, maintenance and overhead burden as one running at 70%, but spreads it across far fewer pieces. Top Glove's improvement from 40% utilisation in 2QFY2024 to 58% in 2QFY2025 is therefore the mechanical explanation for most of the earnings swing — the company itself attributed the stronger results to the surge in sales and the higher utilisation rate, which enabled cost efficiencies.
For FY2025 as a whole, management has maintained a target utilisation rate of 70%, even though the second quarter fell short of it at 58%. The path there is deliberately conservative. Executive director Ng Yong Lin explained that the group plans to maximise the utilisation of plants that are already running before it restarts operations at idle and temporarily shut-down factories, and that restarts will be planned "according to the incoming orders." That sequencing is a lesson learned from the pandemic-era overexpansion: bringing dormant capacity back online too early locks in costs before the revenue arrives.
Why 70% is the number that matters
The gap between 58% and 70% is where the second-half story lives. Closing it requires roughly a fifth more output from the running asset base, or a combination of fuller running plants and carefully chosen factory restarts. If Top Glove hits 70%, the fixed-cost absorption should push margins meaningfully above the current thin levels; if utilisation stalls in the high-50s, the 43-billion-piece target and the profit trajectory come under pressure simultaneously. Investors should treat every future utilisation disclosure as the primary vital sign of this recovery.
Tariffs redraw the map: Washington's China problem becomes Kuala Lumpur's opportunity
The most consequential external force in this story is American trade policy. Top Glove's founder and executive chairman, Tan Sri Dr Lim Wee Chai, spelled out the mechanics at the briefing: the US tariff on imported Chinese medical gloves rose from 60% to 70% in March 2025, while the levy on non-medical gloves jumped from 28% to 48%. His conclusion was blunt — with tariffs that large, Chinese players are "no longer competitive" in the United States from March onward.
For Malaysian producers, this is the demand-redirection dividend. American importers of examination and surgical gloves who previously sourced from China because of its cost advantage now face a tariff wall that erases it. Malaysia — with the world's deepest glove-manufacturing ecosystem, centred on the Klang Valley — is the only supplier with the installed capacity to absorb a meaningful share of that demand at short notice. Top Glove said it is targeting further sales growth in the US precisely on the back of these tariffs, and its North American volumes already rose 13% quarter on quarter in 2QFY2025.
But the tariff advantage comes with a structural caveat that the quarter's data already illustrates. Goods that Chinese factories cannot sell into the United States do not vanish — they get redirected. Top Glove flagged exactly this dynamic in Europe, where Chinese trade diversion is intensifying competition even as Malaysian volumes there fell 23% quarter on quarter. In other words, Washington's tariff wall protects Malaysian producers in America while making Chinese producers more aggressive everywhere else. The net effect for Top Glove depends on how much of the US gain outweighs the ex-US price pressure — a balance that will vary quarter by quarter with every adjustment in American tariff policy.
The regional mix: Europe still towers, America is surging, the map is tilting
The geographic breakdown of Top Glove's second-quarter sales volumes shows an industry in transition. Europe remained the single largest market at 40% of volumes, followed by North America at 23%, Asia at 22%, Latin America at 8%, the Middle East at 4% and Africa at 3%. Yet the direction of travel tells a different story than the static shares:
- Europe (40% of volume): down 23% quarter on quarter, though flat year on year — a market where China's diverted goods are pressuring both volumes and prices.
- North America (23%): up 13% quarter on quarter — the tariff beneficiary, and the region management expects to keep growing.
- Asia (22%): a steady base with long-run demographic tailwinds in healthcare consumption.
- Latin America (8%), Middle East (4%), Africa (3%): smaller but strategically important developing markets where the company says it can sell more.
If the current trends persist through the second half, North America's share of Top Glove's mix should keep climbing while Europe's dominance erodes — a historic tilt for an industry that has long depended on European healthcare systems as its anchor customer. The developing-market tail, meanwhile, is the hedge: Latin America, the Middle East and Africa together already account for 15% of volumes, and glove usage in those regions has structural room to grow as hospital infrastructure expands. Management explicitly counts "opportunities for us to sell more to other developing countries" among the reasons it can hold the 43-billion-piece target even with a weak Europe.
Costs are rising too: the minimum wage and the EPF levy
The recovery is happening against a distinctly more expensive domestic backdrop. Malaysia's minimum wage increase took effect in February 2025, and the government plans a mandatory 2% Employees Provident Fund (EPF) contribution for foreign workers — a significant change in a labour-intensive industry that relies heavily on migrant employment. Second Finance Minister Datuk Seri Amir Hamzah Azizan said the mandatory 2% EPF contribution is expected to be implemented by the fourth quarter of 2025.
Top Glove quantified the combined impact with unusual precision. Executive director Ng Yong Lin noted that the two changes would add RM2.65 million to monthly labour costs — RM2.4 million from the minimum wage increase and RM228,000 from the 2% EPF contribution for foreign workers. Managing director Lim Cheong Guan framed that burden as roughly 1% of cost per carton, the industry's standard unit measure.
Is 1% of cost per carton manageable? In isolation, yes — especially with raw-material prices falling, which gives the company some offset. But the timing is awkward: the cost increase lands exactly when average selling prices are still recovering from their lows and when Chinese competitors, barred from the US, are discounting aggressively in every other market. A glove maker that must fund a RM2.65 million monthly step-up in labour costs while fighting a price war in Europe has less room to use price flexibility as a weapon. This is the quiet tension inside the turnaround story — the same quarter that brought back profits also brought permanently higher costs.
Dividends and the share price: a market that has not yet been convinced
Top Glove's dividend policy promises 50% of net profit, but payments were suspended during the loss-making stretch. At the briefing, Lim Cheong Guan said that if the group ends FY2025 with a full-year profit, it hopes to resume paying dividends. That is a conditional commitment, and the condition — a full-year profit — is not yet secured, since a weak third quarter could still erase the first half's RM35.76 million.
The equity market's verdict remains sceptical. On the day of the briefing, Top Glove shares ended two sen, or 2.2%, lower at 89 sen, valuing the group at RM7.31 billion. The stock was down 33.58% year to date at that point — a striking divergence from the improving fundamentals. The message from that price action is that investors have heard turnaround promises before and are waiting for utilisation to reach the promised 70%, for the 43-billion-piece target to be confirmed by half-year data, and for margins to fatten enough to make a resumed dividend meaningful. At 89 sen and RM7.31 billion of market value, the shares price in recovery as a possibility rather than a certainty.
What to watch from here: the recovery checklist
For readers tracking Top Glove — or the wider Malaysian glove sector it leads — the coming quarters resolve around a small set of observable markers:
- Half-year sales volumes: whether 2HFY2025 shipments accelerate enough to reach the 43-billion-piece FY2025 target, given 1H came in slightly below half.
- Utilisation: progress from 58% toward the maintained 70% target, and whether restarts of idle factories are genuinely order-driven.
- US tariff policy: any widening, pausing or narrowing of the 70% medical and 48% non-medical levies on Chinese gloves, which directly sets the size of Malaysia's pricing advantage.
- European competition: whether Chinese trade diversion keeps pressuring volumes and prices in the region that still accounts for 40% of Top Glove's sales.
- Cost trajectory: absorption of the RM2.65 million monthly labour-cost increase and the 2% EPF levy for foreign workers expected by 4Q2025.
- Raw materials: continued decline in input prices that supports flexible glove pricing.
- The dividend decision: whether a full-year FY2025 profit materialises, triggering the resumption of the 50% payout.
Bottom line
Top Glove's second quarter of FY2025 delivered what the glove sector has been promising for two years: a real profit, real revenue growth of 60.6%, and real operational improvement in utilisation from 40% to 58%. The tariff-driven tilt in US–China trade flows gives Malaysian producers their strongest competitive position in years, and management's 43-billion-piece target signals conviction that the second half will deliver the volumes. But the same forces cut both ways — Chinese diversion is battering Europe, domestic labour costs are stepping up permanently, margins remain thin at RM30.28 million of quarterly profit, and the share price, down 33.58% year to date at the time of the briefing, shows a market demanding proof rather than narrative. The turnaround is real; whether it is durable will be decided by utilisation, tariff durability and price discipline over the remainder of 2025.
Latest Reports

RZD changes return fees for tickets purchased from December

Genentech breaks ground on its Hillsboro expansion

Why available capital does not close every defence supply gap

Tourists' QR Payments Bring Indonesia $345.7 Million as the Cross-Border QRIS Network Expands

Indonesia Tells Furniture Exporters to Look Beyond the US Market

Leave a comment