
Beats Without Cheers: Why Canada’s Big Six Bank Earnings Failed to Move Investors
When the six largest banks of Canada published their results for the second quarter of 2026 in the final days of May, the headlines read like a victory lap: every member of the group known as the Big Six comfortably beat analysts' earnings expectations. The share-price reaction told a different story. Instead of rallying, two of the six lenders posted notable declines on earnings day — Canadian Imperial Bank of Commerce fell 5.3% and National Bank of Canada dropped 4% — while the shares of the other four were more or less flat. A quarter that, on paper, delivered across-the-board beats left investors visibly unimpressed.
That disconnect between solid results and a cold market is the defining feature of Canadian bank stocks in 2026, and it is not a mystery once the quarter is taken apart. Three forces sat behind the muted reaction: valuations that had already run to historical highs, the composition of the beats themselves — heavy in volatile capital-markets revenue rather than durable lending income — and early cracks in consumer credit quality. This deep dive unpacks each of those forces bank by bank, using the second-quarter season as reported by the Financial Post, and asks what the market's scepticism says about where Canadian banking goes from here.
The second-quarter scoreboard: comfortable beats, a cold reception
Going into earnings week, analysts had broadly anticipated the scenario that ultimately played out. Bank shares had surged over the preceding year, and a variety of valuation metrics suggested the lenders were potentially overvalued — a combination that raises the bar for any positive reaction. As John Aiken, an analyst at Jefferies Inc. (Jefferies), put it: "It would have taken a lot to garner any outside positive reaction, just because of where we sit with the macro, as well as the bank valuations. That upside was going to be very difficult to achieve, and we saw that play out."
The earnings-day scorecard made the mood concrete:
- Canadian Imperial Bank of Commerce (CIBC): down 5.3% on earnings day despite beating expectations — the steepest decline of the Big Six.
- National Bank of Canada: down 4% after a beat that was overshadowed by a surprise compression in its net interest margin.
- Bank of Montreal (BMO): up 0.84%, the best earnings-day reaction among the six, though even that came with analyst caveats.
- The remaining banks: more or less flat — beats absorbed without enthusiasm.
The pattern matters more than any single number. When a sector beats expectations everywhere and the average share-price response is roughly zero, the market is saying that good results are now the baseline, not the catalyst. Expectations had been bid up so far by the previous year's rally that only a surprise of unusual quality could move prices higher — and a quarter driven substantially by capital-markets gains was not it.
When a beat is not enough: the quality-of-earnings problem
The composition of the second-quarter results proved as important as their size. As the Financial Post's reporting stressed, if a bank beat expectations mainly because of gains from its capital markets business, that would not have been enough to push investors into buying more shares. Aiken's explanation was blunt: capital-markets revenues are much more volatile than other business lines, so investors generally will not pay up for gains in that sector.
The volatility discount
This is the quiet arithmetic behind the muted reactions. Underwriting fees from a hot issuance calendar and trading revenue from favourable market conditions can flatter a single quarter enormously, but neither is contractual or recurring in the way that net interest income from a mortgage book or fees from a wealth-management franchise are. Rational investors therefore apply a discount to volatile earnings: a dollar of trading profit is worth less in a valuation model than a dollar of stable spread income, because next quarter's dollar is not assured. When most of the Big Six's beats came from the volatile side of the house, the market's refusal to pay up was not cynicism — it was discipline. The same logic implies that as long as capital markets carry the earnings mix, the sector's multiple will struggle to expand further, no matter how many beats accumulate.
The valuation question: a bar raised by the rally itself
The backdrop to the second-quarter season was a powerful, somewhat surprising rally. The shares of the Big Six had gained about 13.7% on average between the late-May earnings and mid-August 2026, and had been rising for longer: analysts had been cautious on bank valuations for a while even as the stocks kept climbing. In its third-quarter earnings preview, the Financial Post noted that the large Canadian banks' average price-to-expected-earnings ratio stood at 16 in mid-August — well above the historical average of 11.3. Mike Rizvanovic, an analyst at Bank of Montreal, captured the resulting tension: "The elevated multiple remains top of mind for most bank investors with concerns around what is currently priced in and how much downside risk there might be if the quarter doesn't pan out as well as expected. We believe there is a very high bar to getting share prices to rally through the third quarter."
Analysts offered a striking explanation for why global money kept flowing into the sector: investors looking to diversify away from United States dollar assets and AI-heavy stocks amid economic uncertainty turned towards metals, oil, gold and markets that offer a tangible link to resources — and Canada has plenty of those. The banks, as the largest companies in the S&P/TSX composite index, inevitably benefit from that reallocation. In other words, part of the rally in bank shares has less to do with bank fundamentals than with Canada's weight in a resource-linked diversification trade.
Paul Holden, an analyst at CIBC World Markets Inc. (CIBC World Markets), framed the resulting predicament with unusual symmetry: it is hard to say whether bank stocks can continue to push higher, but it is easier to say that the third-quarter results should not be a reason for the stocks to trade lower. That is the sound of an analyst describing a sector priced for perfection — where bad news costs more than good news gains.
Credit: provisions and the stretched Canadian consumer
The second big theme of the quarter lived below the revenue line. Provisions for credit losses (PCL) — the money banks keep aside to tackle loans that may potentially go bad — were expected to play a role in share-price valuations, and they did. Many banks had earlier guided that PCLs would improve in the second half of the year. Then geopolitics intervened: analysts expected the banks to change that outlook following the war on Iran, which put more pressure on an economy already carrying strained household finances.
At CIBC, the credit numbers came in worse than the market had modelled. The bank kept aside a higher amount of money to tackle impaired loans — those where the bank no longer has reasonable assurance of collecting the full principal and interest on time. "PCLs were 14% above our forecast," said Gabriel Dechaine, an analyst at National Bank of Canada. "Upward pressure came from the Canadian personal banking segment… due mainly to higher losses on cards and unsecured personal loans. With increasing scrutiny of Canadian consumer financial health, this quarter's performance could weigh on sentiment for the foreseeable future."
That last sentence is worth dwelling on. Card and unsecured personal loans are the earliest stress points in any consumer credit cycle: they are the first balances households stretch when incomes fail to keep up with housing costs and everyday prices. When losses on those products jump enough to push a major bank's total provisions 14% above forecasts, the natural reading is not a one-off but the visible edge of a broader deterioration — which is exactly why Dechaine tied it to "increasing scrutiny" of consumer financial health and warned about sentiment for the foreseeable future.
The follow-up reporting ahead of the third quarter struck a similar, slightly calmer tone. Matthew Lee, an analyst at Canaccord Genuity Corp. (Canaccord Genuity), observed that "credit remains stretched, but manageable," adding that "the consumer continues to be somewhat challenged in Canada, with stubborn unemployment and limited economic growth likely to weigh on PCLs for the remainder of the year." Crucially, he did not expect credit to become an "impediment to double-digit earnings-per-share growth" in the near term — the consumer is a drag on sentiment and provisions, not (yet) on the growth rate of profits.
Net interest margin: the eight-basis-point surprise
The third force behind the quarter's cold reception was margin direction at National Bank of Canada. The bank beat expectations after strong performance in its capital markets segment, but faced a bit of a backlash due to a decline in its net interest margin (NIM) — the difference between the interest a bank earns on loans and securities and the interest it pays out on deposits. "It was an overall solid quarter other than the downside surprise on NIM," Holden noted. "Sequential NIM compression of eight basis points overshadowed otherwise strong results."
Mario Mendonca, an analyst at Toronto-Dominion Bank (Toronto-Dominion), added a second irritant: National Bank's expense growth was also elevated in the quarter, which stood out in a period when most banks were generating near-record operating leverage — revenue growing faster than costs, the single cleanest marker of efficiency in banking.
Why eight basis points move a share price
Eight basis points of quarterly margin compression sounds trivial; on a bank balance sheet measured in hundreds of billions of dollars it translates into a material amount of annualised spread income, and — more importantly — into a change of direction. Investors extrapolate margins far more aggressively than they extrapolate trading profits, because margins are the closest thing banking has to a recurring annuity. A surprise compression reads as evidence of intensifying deposit competition or unfavourable repricing, and it invites the market to model the pressure persisting for several quarters. That is why a capital-markets beat at National Bank could not offset a margin miss: the two lines carry very different weights in the valuation.
Bank of Montreal: the best reaction — and the debate over its quality
BMO was the only Big Six member whose shares rose meaningfully on earnings day, up 0.84% — the highest among the six. Even that modest gain came with a caveat. Aiken argued that BMO's reliance on capital markets may compel some investors to pause: "While we do not believe that this will fully take away from BMO's perceived results, it does remove some of the lustre."
Dechaine disagreed that the quarter was a one-trick pony. "Other positive elements included a rebound in United States loan growth, with guidance for continued volume growth in the second half," he said, adding that credit performance was better than expected. Those two details matter. A rebound in American lending diversifies BMO's growth away from the stretched Canadian consumer at exactly the moment domestic credit costs are rising, and better-than-expected credit performance runs directly against the sector-wide worry that provisions were about to turn. Of all the second-quarter prints, BMO's arguably combined the beat with the healthiest composition — which is plausibly why it was the only one the market rewarded at all.
CIBC: why the stock checked back
The quarter's sharpest share-price decline, CIBC's 5.3%, deserves its own post-mortem because it condensed every theme of the season into a single reaction. Mendonca's reading was comprehensive: "Given recent performance and relative valuation, a moderating outlook for net interest margins, domestic consumer stress and the nature of the beat (heavy in capital market), we understand why the stock checked back."
Parse that sentence and the 2026 playbook for bank-stock reactions appears in full: a share price that had already run, a margin outlook softening at the margins, a domestic consumer under stress, and a beat built on the most volatile revenue line available. Any one of those might have been forgiven; together they triggered the steepest de-rating of the quarter.
Yet Mendonca was equally clear about what did not break: "Having said that, we feel good about CIBC's strong capital position, improving loan growth and low (loan-to-value ratio) on the large mortgage book." A low loan-to-value ratio on mortgages means borrowers hold substantial equity in their homes — the strongest structural protection a Canadian bank can have against a housing-linked credit shock. CIBC's problem in the second quarter was not the quality of its balance sheet; it was the gap between that quality and the price investors were already paying for it.
A K-shaped economy behind the earnings
Read together, the six results describe an economy running in two speeds at once — what economists have come to call a K-shaped pattern. The upper branch showed up in the capital-markets segments that powered the beats: corporations issuing equity and debt, traders capturing volatility, investment bankers collecting fees. The lower branch appeared in the credit lines: rising losses on cards and unsecured personal loans, stubborn unemployment, limited economic growth, and provisions that refused to fall as quickly as banks had promised.
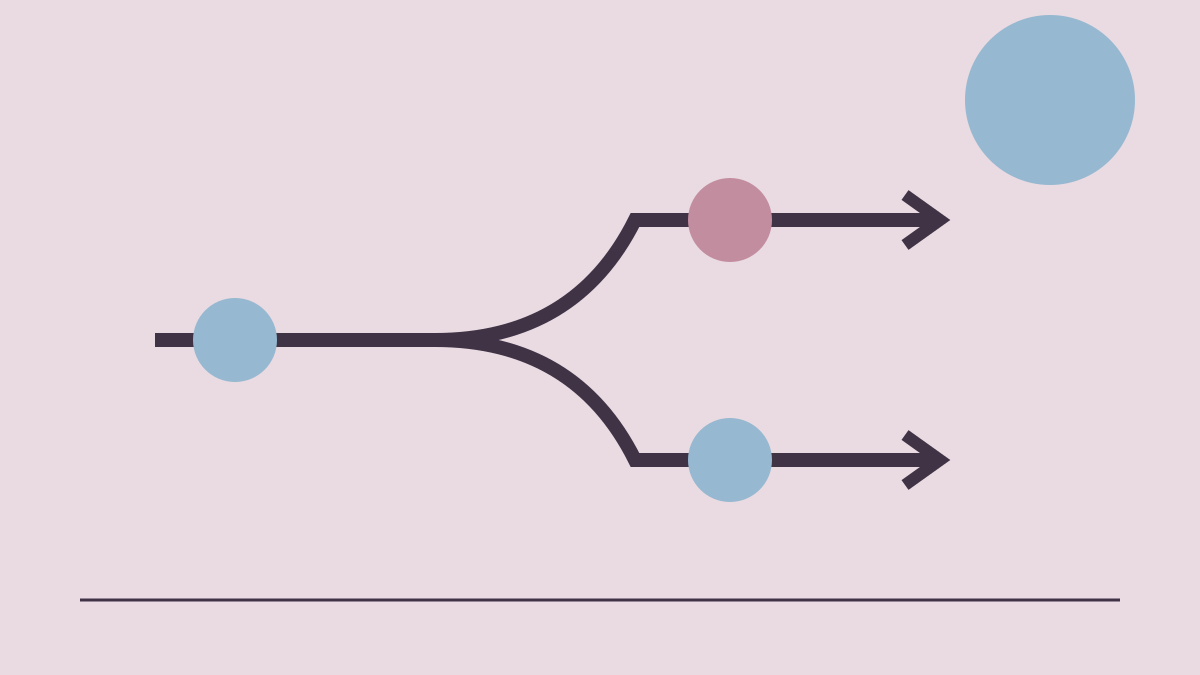
The uncomfortable implication for investors is that both branches run through the same income statement. The affluent end of the economy generates the volatile revenue that flatters quarterly beats; the strained end generates the credit costs that erode them. A bank's reported growth rate therefore conceals which engine is doing the work — and the second-quarter reactions showed that the market has learned to look under the hood. Beats driven by the upper branch earn a volatility discount; losses from the lower branch earn a sentiment penalty. A sector whose earnings mix leans on capital markets while its consumer book deteriorates can keep beating estimates and keep failing to rally — precisely the pattern of the quarter.
There is a third force complicating the picture: the global diversification trade. With investors rotating out of dollar assets and AI-heavy portfolios into resource-linked markets, Canadian bank shares benefit from flows that have nothing to do with domestic banking fundamentals. That support is real, but it is also exogenous — it depends on global appetite for resources, not on NIMs or PCLs. If the rotation fades, the elevated multiples lose one of their quiet pillars at the same time the consumer cycle is still testing the other.
What to watch as the third quarter lands
The third-quarter reporting season opens against a capital-markets backdrop that remains exceptionally strong. Canada's financial sector raised about $376 billion through 586 deals in the first six months of 2026, up 21.5% from the $309.3 billion raised in the same period a year earlier, according to Financial Post Data — a pace that puts the sector on track to surpass the $597 billion recorded in all of 2025, the highest annual total since 2010. That flow of issuance is the fuel for the very capital-markets beats the market refuses to reward, and it frames the central tension of the coming quarter: activity is booming, but its valuation weight is capped by volatility.
The checklist for the third quarter follows directly from the second:
- Composition of the beat: how much of any upside comes from capital markets versus domestic banking, wealth and lending — the single biggest determinant of the share-price reaction.
- PCL trajectory: whether provisions begin to improve as banks had originally guided for the second half, or whether card and unsecured-loan losses keep pushing them above forecasts.
- NIM direction: any repeat of National Bank-style sequential compression would spread margin anxiety across the group; stabilisation would remove one overhang.
- Deployment of excess capital: "Banks have a significant amount of excess capital, and we believe those that can deploy more capital and at higher returns could be the relative winners going forward," Holden argued — watch dividends and buyback announcements as the proof.
- The valuation multiple: whether a price-to-expected-earnings ratio near 16 against a historical average of 11.3 survives another quarter of capital-markets-heavy beats.
- The non-sufficient-funds fee cap: the third quarter reflects the full impact of Ottawa's March decision to cap NSF fees at $10, down from as much as $48. "The impact, based on the guidance we received from the banks, appears very manageable," Rizvanovic said, noting that RBC and TD would likely feel it most given their larger retail deposit bases.
- Consumer data: unemployment and household delinquency trends outside the banks' own reports — the raw material for the next revision of PCL guidance.
Bottom line
The second quarter of 2026 marked the moment Canadian bank stocks stopped being rewarded for being good. Every Big Six member beat expectations, yet the average reaction hovered around zero, with CIBC down 5.3% and National Bank down 4% — declines driven not by earnings weakness but by valuation stretch, a beat mix heavy in volatile capital-markets revenue, an eight-basis-point margin surprise and the first loud signals of consumer credit stress in cards and unsecured loans. The market has redefined what counts as a good quarter: beats are the baseline, and only durable, high-quality earnings can still move prices.
Heading into the third quarter, the sector carries a rare combination — booming issuance activity, record-track capital raising of roughly $376 billion in the first half, excess capital looking for deployment, and a multiple near 16 times expected earnings against a historical norm of 11.3. Add a consumer that is stretched but not broken, and a global diversification trade propping up valuations from outside. Whether the banks can convert all of that into earnings the market will actually pay up for is the open question of the second half of 2026 — and the second quarter proved that the market will grade the answer strictly.
Latest Reports

RZD changes return fees for tickets purchased from December

Genentech breaks ground on its Hillsboro expansion

Why available capital does not close every defence supply gap

Tourists' QR Payments Bring Indonesia $345.7 Million as the Cross-Border QRIS Network Expands

Indonesia Tells Furniture Exporters to Look Beyond the US Market

Leave a comment