
India's Growth Gears Shift Down: Inside the 2024 Consumption Squeeze and the RBI's December Dilemma
India entered the final quarter of 2024 carrying a number nobody in New Delhi wanted to repeat out loud: 5.4%. That was the pace of gross domestic product growth in the July–September quarter — a seven-quarter low, well below the consensus of economists and beneath the Reserve Bank of India's own projection of about 7% for the period. For an economy that had expanded by more than 8% in the previous fiscal year and had grown accustomed to being described as the bright spot on the global growth map, the print was more than a statistical wobble. It reopened a debate about how durable the country's consumption-led expansion really is, and about which households have been carrying it.
The slowdown did not arrive as a single shock. It arrived as a stack of them: urban families quietly cutting back, real wages contracting for the first time since the pandemic, listed companies posting their weakest quarter in years, and inflation climbing back above the central bank's tolerance band just as policymakers were preparing to ease. This analysis unpacks the mechanics of the 2024 growth moderation — what the data actually show, where the pressure points sit, and why a meaningful group of economists still reads the picture as stabilisation rather than decline.
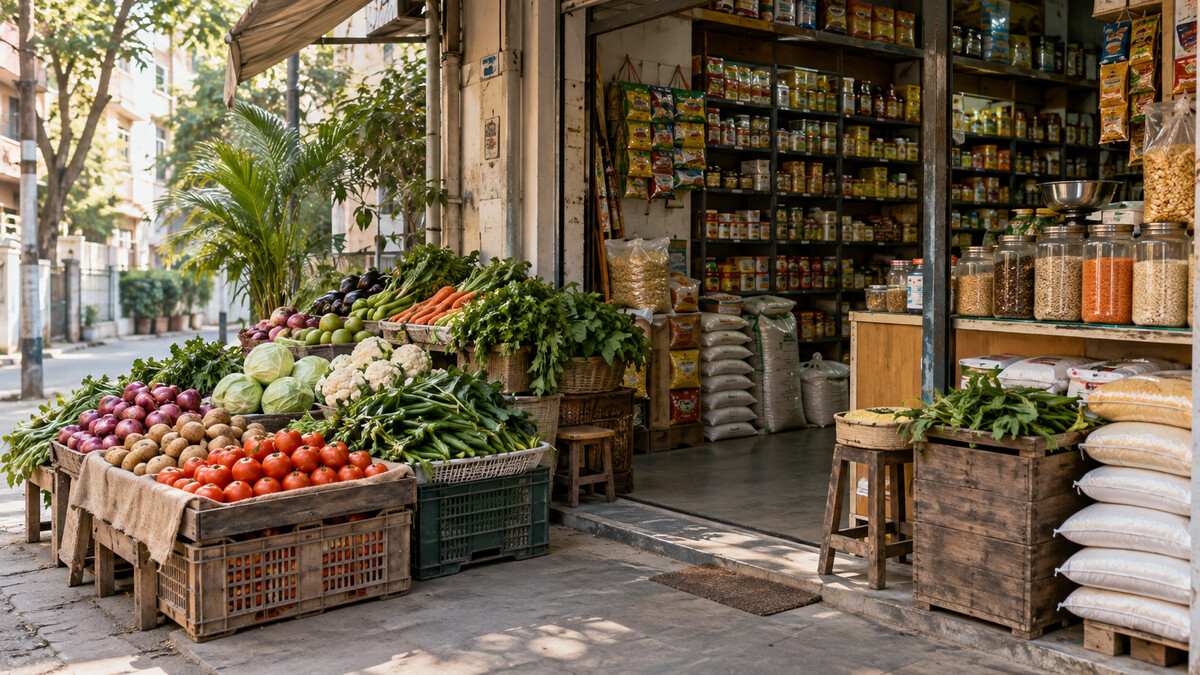
A seven-quarter low resets the forecast board
The July–September reading of 5.4% immediately forced a round of downgrades. Economists at Goldman Sachs Group — Santanu Sengupta and Arjun Varma — cut their projection for the fiscal year ending March 2025 to 6% from 6.4%. State Bank of India (SBI), the country's largest lender, warned that full-year growth was likely to slip below 6.5% once the weak second quarter was folded into the arithmetic. The broader analyst consensus that formed in the following weeks settled in a 6%–6.8% range for the year to end-March, against the central bank's own forecast of 7.2%, and several houses cited the likelihood of a Reserve Bank rate cut as early as February as growth risks accumulated.
The gap between those numbers matters beyond bookkeeping. The post-pandemic growth story has been unusually dependent on domestic demand: exports played a modest role, while urban consumption, government capital spending and a services boom did the heavy lifting. When a demand-led economy decelerates, the first question is not whether factories lost orders but whether households stopped spending — and in 2024 the answer began to look uncomfortably close to yes, at least in cities. That is why a single quarterly print rippled so quickly through earnings calls, brokerage notes and monetary policy debate.
Corporate India's worst quarter in four years
The earnings season that followed the GDP release confirmed that the chill had reached the corporate sector. Indian listed companies registered their weakest quarterly showing in more than four years for July–September, and brokerage Motilal Oswal projected Nifty earnings growth of a modest 5% for the fiscal year — the first single-digit outcome in five years. Between fiscal 2020 and fiscal 2024, earnings of the companies the brokerage covers had compounded at roughly 21% a year; in the July–September quarter they contracted by about 1% year on year, while Nifty-50 earnings grew just 4% — the softest readings in eight and seventeen quarters respectively.
Behind the aggregate, the damage was uneven. Commodities dragged the index; banking, financial services and insurance showed asset-quality stress; and consumption-facing companies turned into the quarter's clearest weak spot. About half of the constituents of the NSE Nifty 50 Index missed consensus estimates in their second-quarter results, according to data compiled by Bloomberg. Even the country's most resilient conglomerate was not immune: more than 15 Tata Group companies, including Tata Consultancy Services, Tata Motors, Tata Steel and Tata Power, reported single-digit revenue growth in the first half of the fiscal year, with profits slowing at a similar number of group firms.
Tata's counter-cyclical wager
The response inside Tata Sons, the group's holding company, offers a window into how India's largest business houses are reading the moment. Chairman N Chandrasekaran urged group chief executives to pursue growth aggressively despite mounting uncertainty at home and abroad, according to an Economic Times report based on people familiar with the matter. In internal strategy sessions and business reviews, Chandrasekaran stressed boldness of ambition: margins can be repaired over time, he argued, but growth opportunities must be seized when they appear. In a high-rate environment where markets punish any sign of weakness, that instruction is as much a defence of valuation as it is a business strategy — and it signals that at least part of corporate India expects the demand pause to be temporary.
Private investment waits for the consumer to return
The corporate numbers carry a second-order effect that may matter more than the headline itself: the investment cycle. As The Economic Times put it in its assessment of the quarter, the economy is cooling faster than anticipated and industry is bearing the brunt — a combination likely to delay the revival in private investment as companies await a resumption in consumer spending. In a high-interest-rate environment, weak earnings do not merely disappoint markets; they raise the hurdle rate for every new factory, warehouse and product line that was supposed to be approved in the coming board cycle, and markets are likely to feel the chill as corporate performance weakens against expensive money.
The earnings arithmetic shows how abrupt the turn has been. Since August 2024, Motilal Oswal reduced its FY25 Nifty EPS estimates by 5%, and the universe the brokerage covers moved from a compound annual growth rate of about 21% between fiscal 2020 and fiscal 2024 to a year-on-year contraction in the July–September quarter. Crucially, the weakness is concentrated rather than generalised: excluding the commodities segment, second-quarter earnings were broadly in line with expectations, with consumption emerging as the major weak spot and the banking, financial services and insurance space showing asset-quality stress. That pattern — a consumer-led drag transmitting into bank balance sheets — is precisely the configuration in which private capital expenditure plans get postponed rather than cancelled, and it is why the second-half trajectory of government spending and rural demand carries so much weight in every forecast of the recovery.
The wage squeeze behind the consumption stall
If corporate earnings explain the supply side of the slowdown, wages explain the demand side. Inflation-adjusted employment costs at listed non-financial companies — a widely used proxy for real urban wages — fell 0.5% year on year in the July–September quarter, according to data from Elara Securities: the first contraction since the pandemic. A series from Citi tells a similar story in slower motion: real wage-cost growth at listed Indian firms stayed below 2% in all three quarters of 2024, against a ten-year average of about 4.4%. For the first time in the post-pandemic cycle, the urban consumer was running to stand still.
For the urban middle class the arithmetic has been brutal. Food inflation stayed elevated through the year; input costs such as palm oil, coffee and cocoa pushed up the price of packaged goods; and several fast-moving consumer goods manufacturers hinted at further price increases even as their own margins compressed in the September quarter. The result surfaced in the numbers of consumer bellwethers: Maruti Suzuki and Hindustan Unilever both posted weaker earnings and pointed to languishing urban middle-class spending. Garima Kapoor, an economist at Elara Securities, linked the squeeze to slow hiring in the technology sector and muted profitability in manufacturing, both of which cap real income growth precisely when inflation is elevated. Samiran Chakraborty, Citi's chief India economist, added declining household savings and tighter rules on personal lending to the list of drags on urban consumption.
The politics of the number followed quickly. The opposition Congress party argued that the July–September deceleration reflected stagnant wages for crores of workers — a framing the government disputes, but one that captures why this slowdown feels qualitatively different from earlier, investment-led pauses: the pressure now sits on the household balance sheet, not on the project pipeline.
From soaps to cars: what the middle class stopped buying
The breadth of the pullback is what turned a soft quarter into a national conversation. Consumers are now cutting back on everything from soaps to cars, and the margin declines reported by leading FMCG companies in the September quarter — attributed to higher input costs and food inflation — show manufacturers absorbing part of the shock before hinting at price hikes of their own. Slowing urban spending over the three to four months into December not only hurt the earnings of the largest consumer-goods firms; it raised questions about the structural nature of India's long-term economic success, because the categories that weakened are exactly those through which a rising middle class normally announces itself.
Since the end of the pandemic, India's economic growth has been driven in large part by urban consumption — and that engine now appears to be changing gear. Several economists caution against reading the moderation in car and packaged-goods sales as decline: in their framing, urban demand in India is stabilising rather than slowing, an expected adjustment after the "revenge-shopping" boom of the months immediately following the Covid-induced shutdowns had pushed consumption above trend. On that view, 2024 is not the year the consumer broke but the year the base effect caught up with him — a distinction that only the wage and savings data of 2025 can finally settle.
Inflation above the band: the central bank's December dilemma
The Reserve Bank of India entered December facing the least comfortable configuration a central bank can hold: growth slowing while inflation rises. Consumer price inflation climbed to 6.21% in October, a fourteen-month high and above the upper edge of the 2%–6% target band, driven largely by volatile vegetable prices but reinforced by a broadening of pressure — input-cost inflation at its fastest since July and output-price increases the most pronounced in more than eleven years. Inflation weighed simultaneously on corporates, whose margins compressed, and on consumers, who tightened their purse strings.
Markets had been pricing a first rate cut in December; after the inflation print, most economists in a Reuters poll pushed that expectation into early 2025. The six-member Monetary Policy Committee chaired by Governor Shaktikanta Das was scheduled to meet on December 4–6, with the decision of the rate-setting panel to be announced on December 6; the benchmark rate was widely expected to stay unchanged for one more review, alongside the real possibility that the committee would also trim its growth forecast in light of the second-quarter disappointment. Dhruv Agarwala, chief executive of Housing.com and PropTiger.com, captured the shift in mood: the sharp rise in inflation had initially seemed to rule out a cut, but with decelerating growth becoming the pressing concern, the Reserve Bank might still consider easing at the coming meeting despite inflationary pressure and a difficult global backdrop.
The policy bind is structural as much as cyclical. Rates held high to anchor inflation now jeopardise the very growth the economy needs to absorb a young labour force, while a premature cut risks unanchoring price expectations in a year when food supply has already proved fragile. That tension turned the December meeting into one of the most closely watched policy events of the year and set up 2025 as a test of whether monetary easing can restart demand without reigniting prices.
Silver linings: rural demand, staples and the second-half case
Against the gloom, a second narrative runs through the same data. Motilal Oswal expects the corporate earnings outlook to improve in the second half of the fiscal year as government spending resumes, the Kharif crop turns out robust and rural demand revives; the first half, the brokerage notes, was weighed down by flat public expenditure and excess rainfall that disrupted demand in rural and semi-urban markets. HSBC Global Research, analysing 100 growth indicators, found that 55% of the economy was still on an upward trend — down from 65% a quarter earlier, but with the majority of indicators positive and investment activity, especially construction and public-sector-led projects, holding up.
The consumption data themselves contain a reassuring detail. Staples and essentials largely bucked the slowdown, with volume sales growing at mostly double-digit rates in categories such as edible oil, spices, atta, toothpaste, rice and pulses, according to companies and market researchers including Adani Wilmar, Tata Consumer Products, Colgate, LT Foods, Spencer's Retail, NielsenIQ and Kantar — and most of them expected the trend to continue into the October–December quarter. Crucially, the classic signatures of a demand crisis did not materialise: consumers were not trading down to smaller packs, switching en masse to cheaper local brands or moving to loose products. Several economists therefore read urban demand as stabilising after the post-pandemic "revenge shopping" boom rather than collapsing — an adjustment in the level of spending, not a breakdown of the consumer economy.
What to watch as 2024 closes
The December and January data flow will decide which of the two narratives — squeeze or stabilisation — carries into 2025. Practitioners, policymakers and investors are watching a short list of variables:
- The Monetary Policy Committee's decision and, more importantly, the language around its growth and inflation forecasts for the January–March quarter.
- Real wage proxies in the October–December quarter: a return to positive territory would remove the single biggest drag on urban consumption.
- The pace of government capital spending in the second half, the variable most brokerages treat as the swing factor for corporate earnings.
- Rural demand indicators after the Kharif harvest, including two-wheeler and entry-level vehicle sales and fast-moving consumer goods volumes outside the metros.
- Nifty earnings revisions for the second half: whether the projected 5% full-year growth proves to be a floor or a ceiling.
- The trajectory of vegetable and food prices into the January–March quarter — the volatile component that has kept headline inflation above the band and a rate cut out of reach.
- Asset quality in unsecured retail lending, the channel through which a consumption slowdown can become a credit slowdown.
The 2024 slowdown is, in the end, a story about the price of a consumption-led model. The same urban households that powered the recovery now set its speed limit, and their balance sheets — wages, savings, access to credit — have become the macroeconomic variables that matter most. Whether the gears shift back up in 2025 will depend less on any single policy lever than on whether incomes start growing faster than the prices of the baskets those incomes buy.
Latest Reports

RZD changes return fees for tickets purchased from December

Genentech breaks ground on its Hillsboro expansion

Why available capital does not close every defence supply gap

Tourists' QR Payments Bring Indonesia $345.7 Million as the Cross-Border QRIS Network Expands

Indonesia Tells Furniture Exporters to Look Beyond the US Market

Leave a comment